
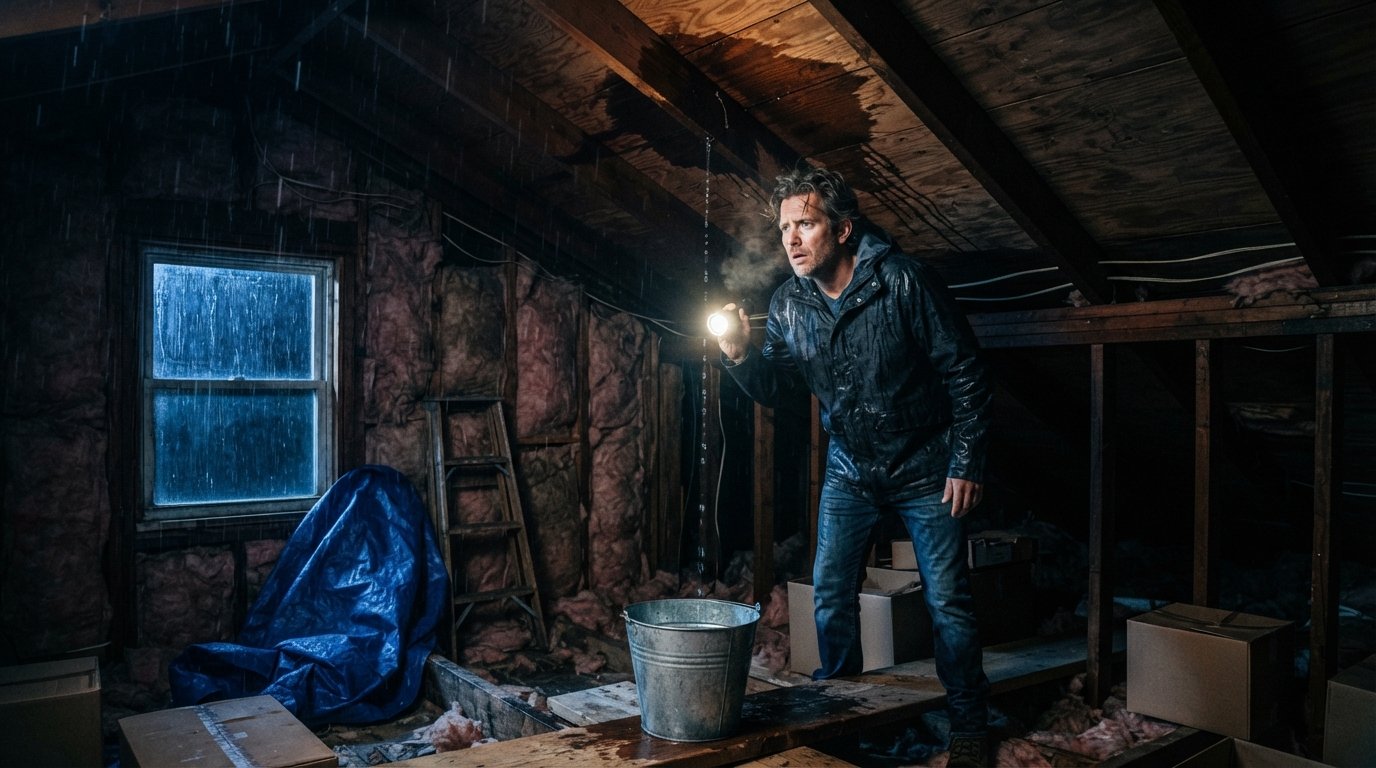
Emergency Loan for Sudden Home Roof Repair
A loan for unexpected home roof repair emergency can stop damage fast. Compare short-term options and get matched with lenders in minutes.
By Dylan Patterson
A dripping ceiling at 2 a.m. or a missing shingle after a storm is more than a nuisance: it is a financial emergency that will not wait for your next paycheck. Roof damage escalates fast. A small leak can rot decking, ruin insulation, and spawn mold within days, turning a $600 patch into a $6,000 structural repair. When you do not have the cash on hand, a loan for unexpected home roof repair emergency can bridge the gap so you can protect your home and your budget at the same time.
This guide walks you through the real costs of emergency roof repairs, the fastest funding options, and how to choose a loan that helps rather than hurts. You will also see how a loan connection service like LendersCashLoan can match you with third-party lenders who may offer short-term personal loan options, even if your credit is not perfect.
Why Roof Emergencies Cannot Wait for Savings
Roof problems rarely announce themselves politely. You might notice a brown stain on the ceiling, a shingle in the yard, or a sudden draft during a rainstorm. By the time water is visibly entering your home, the damage underneath is usually worse than it looks. Water travels along rafters and pools in unexpected places, which means the visible leak is often not the actual source.
Insurance can help, but it does not pay instantly. A claim may take weeks to process, and in many cases the homeowner must pay a deductible or cover repairs upfront and seek reimbursement later. Meanwhile, tarping, emergency patching, and mold prevention cannot wait. That timing gap is exactly why a loan for unexpected home roof repair emergency exists as a category of short-term borrowing.
There is also a safety dimension. A compromised roof can threaten electrical wiring, cause ceiling collapse, or expose your family to the elements. Treating roof repair as an urgent expense, not a routine home improvement project, is the first step toward making a smart funding decision.
What Emergency Roof Repairs Typically Cost
Roof repair costs vary widely by region, roof material, and the extent of damage. A small patch might cost a few hundred dollars, while replacing a section of decking and shingles can run into the thousands. Understanding the ballpark helps you decide how much to borrow and which loan type fits best.
- Minor patch or shingle replacement: $300 to $1,500
- Flashing repair or leak sealing: $500 to $2,500
- Partial roof section replacement: $2,000 to $7,500
- Emergency tarping and water mitigation: $400 to $3,000
- Full roof replacement after severe storm damage: $8,000 to $20,000 or more
These numbers explain why so many homeowners turn to short-term financing. A loan request through a connection service can often be completed in minutes, and funds may arrive as soon as the next business day, which is critical when a contractor needs a deposit to start emergency work.
Before you borrow, get at least two written estimates. A reputable roofer will separate emergency mitigation (stopping the water) from permanent repair (fixing the cause). This distinction helps you borrow only what you need right now and plan the rest strategically.
Loan Options for an Unexpected Roof Repair Emergency
Not all emergency loans are the same. The right choice depends on how much you need, how fast you can repay, and whether you can provide collateral. Below are the main categories homeowners consider.
Personal Loans and Installment Loans
Personal loans and installment loans provide a lump sum that you repay in fixed monthly payments over a set term. Because they are unsecured, you do not risk your home as collateral. They are a strong fit for roof repairs in the $1,000 to $5,000 range. A loan connection service can submit your information to multiple third-party lenders at once, which improves your odds of seeing an offer that matches your budget.
Payday and Cash Advance Loans
Payday loans and cash advances are designed for very short terms, usually until your next payday. They can be useful for a small emergency patch, but they are expensive if rolled over. Use them only when the repair cost is modest and you are confident you can repay on time. For larger roof repairs, an installment loan with a longer term is usually more manageable.
Home Equity and Contractor Financing
If you have significant equity, a home equity line of credit may offer lower rates, though approval can take longer than a roof leak allows. Some roofing companies also offer in-house financing. Compare these options carefully, because contractor financing sometimes carries higher rates or less transparent terms than a personal loan from a lending network.
For a deeper look at how fast funding works in urgent situations, see this guide on emergency personal loans for fast cash, which explains the application flow and what lenders typically review.
How to Get a Roof Repair Loan Fast
Speed matters, but so does accuracy. A rushed application with wrong information can delay funding or lead to a denial. Follow a simple sequence to keep the process smooth.
- Document the damage with photos and a written estimate from a licensed roofer.
- Decide how much you need for emergency mitigation versus full repair.
- Submit one online request through a loan connection service rather than applying to many lenders separately.
- Review each offer for APR, fees, repayment term, and total cost.
- Accept the offer that fits your budget and provide any verification documents promptly.
Most connection services take under five minutes to complete a request. After that, you may receive multiple offers from independent lenders. The key is to compare the total repayment amount, not just the monthly payment. A lower monthly payment over a longer term can cost far more in interest.
If you are exploring general borrowing options, you can also compare offers through FreeQuotes.Loans, an online loan comparison and connection service that helps individuals in the United States find personalized loan offers from a network of third-party lenders. It is a useful starting point for urgent needs like roof repairs, medical bills, or car emergencies.
Qualifying With Less-Than-Perfect Credit
Many homeowners worry that a past bankruptcy, repossession, or low credit score will block them from emergency funding. The reality is more nuanced. Short-term lenders in a connection network often focus on current income and banking history rather than credit alone. That means you may still qualify for a loan for unexpected home roof repair emergency even if your credit profile is not ideal.
Typical requirements include being at least 18 years old, having a steady source of income, an active checking account, and valid contact information. Some lenders may ask for proof of income or a bank statement. Providing these upfront speeds up the decision.
Keep in mind that rates for bad credit loans tend to be higher. That is the trade-off for accessibility. Borrow only what you can reasonably repay, and avoid stacking multiple loans at once. If your roof repair is large, ask whether a co-borrower with stronger credit could join the application to improve terms.
Protecting Yourself From Predatory Terms
Emergency situations make people vulnerable, and some lenders exploit that. Protect yourself by reading every agreement before you sign. Look for clear disclosure of the APR, finance charges, late fees, and prepayment penalties. If a lender pressures you to sign immediately or refuses to provide written terms, walk away.
Also be cautious of unsolicited calls demanding upfront fees for a guaranteed loan. Legitimate connection services do not guarantee approval, and they do not charge you to submit a request. Lenders in a reputable network will verify your information and disclose terms clearly.
Finally, think about the long term. A roof repair loan solves an immediate problem, but it adds a monthly obligation. Build the payment into your budget before you accept the offer. If the numbers do not work, consider a smaller emergency patch now and a larger planned repair later.
Smart Steps After You Secure the Loan
Once funding is in place, your focus shifts to managing the project and the debt. Hire a licensed, insured roofer and avoid paying the full amount upfront. A common arrangement is a deposit for materials, with the balance due upon completion and inspection. This protects you if the work is incomplete or substandard.
Keep all receipts and contracts. If your insurance eventually reimburses part of the cost, you may be able to pay down the loan faster and reduce interest. Setting up automatic payments can also help you avoid late fees and protect your credit score.
Most importantly, treat the loan as a bridge, not a permanent solution. Rebuild a small emergency fund as soon as the roof is fixed, even if it starts with $20 a week. The next home crisis will be far less stressful when you have a cushion.
A sudden roof repair is one of the most stressful home emergencies a person can face. With the right loan for unexpected home roof repair emergency, you can stop the damage, protect your home, and spread the cost over time. Compare offers carefully, borrow responsibly, and get your roof, and your finances, back on solid ground.